
Under the education loan-old age complimentary system, organizations is also matches benefits, to a specific payment, when a member of staff tends to make a qualifying student loan commission to their employer-sponsored 401(k), 403(b), 457, otherwise Effortless IRA account.
Rather than deposit a fraction of your own salary on your 401(k) to maximum your boss meets – basically making you totally free currency – you’re going to get an equivalent company meets work for after you create a great being qualified mortgage fee. A matching contribution the most strong old-age deals professionals getting specialists to expand a lot of time-lasting money.
Think of, 401(k) student loan suits have to follow a comparable meets fee, qualifications, and you may vesting guidelines since the income deferrals.
One boss giving qualifying agreements provide a good 401(k) education loan match because an employee benefit. If the interested, believe contacting your employer’s Hr to tell them in the the fresh opportunity. It may be as simple as giving an email.
Relieves financial strain on personnel
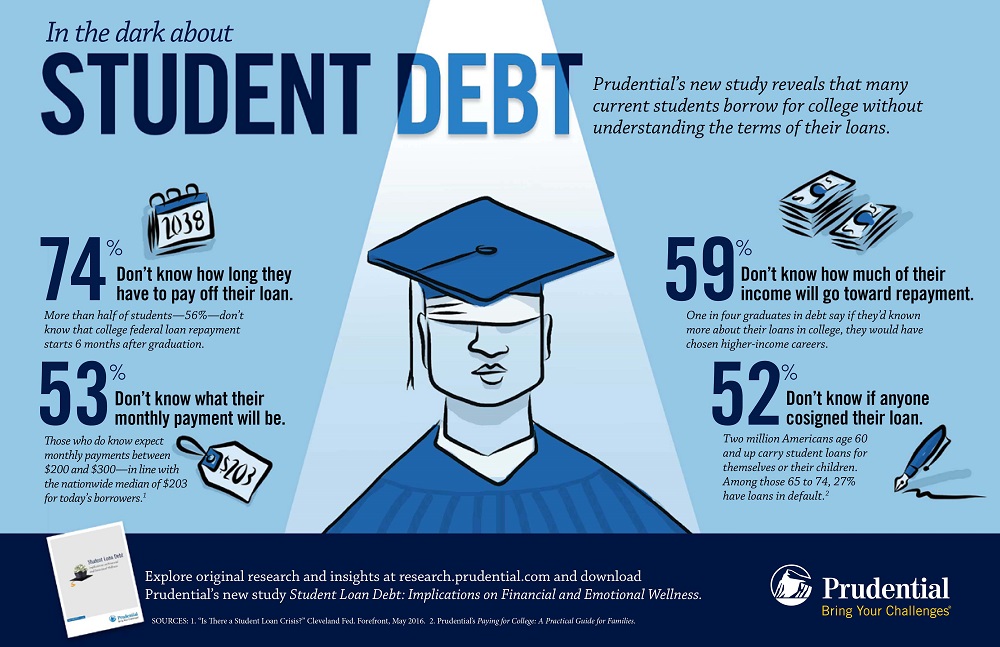
Of many U.S. employees not be able to pay off the student loan personal debt, usually failing to contribute regularly to their place of work old-age plans and you may losing the additional advantageous asset of boss-coordinating benefits. By the forgoing their 401(k) or other preparations, teams and lose out on many years of income tax-deferred or income tax-free development.
The brand new Safer Act dos.0 relieves certain professionals of this financial filters by allowing all of them to make totally free retirement currency when they make qualifying student loan money.
“Removing education loan obligations can benefit the latest savings of the moving forward household info out-of loans installment to resource and you will purchasing, and additionally improved private production,” explains Greenip.
Assists businesses attract and you can maintain ability
A pension plan such as for instance a beneficial 401(k) otherwise your retirement is among the a lot https://speedycashloan.net/loans/tribal-loans/ more noteworthy masters usually tried by the pros. But not all the practices give employer-matching benefits, businesses that do generally have a less complicated time attracting and sustaining talented personnel.
A 401(k) match window of opportunity for paycheck deferrals and you can qualifying education loan payments is attractive so you’re able to U.S. professionals hoping to get the best of each other globes. Moreover, professionals is generally even more motivated to sit before the fund into the the senior years package was fully vested (three to five many years).
Internal revenue service some tips on 401(k) education loan suits system
First, the Irs provided nothing some tips on the applying, along with the thing that was experienced a good “qualifying” student loan payment and exactly how employers was basically anticipated to track and you may approve the employees’ education loan efforts.
“Employee deferrals so you’re able to senior years preparations is actually administered of the companies by themselves, making it not too difficult to trace benefits,” Greenip explains. “Once the businesses dont tune education loan payments, which adds a piece out-of complexity and you will management help which can be needed to provide the work with.”
With the August 19, the fresh new Irs provided meantime ideas on 401(k) education loan matches, especially toward Area 110 of your own Safe 2.0 Act.
Which qualifies having a good 401(k) student loan match?
- Old-age preparations that be eligible for a student loan match is actually 401(k)s, 403(b)s, Effortless IRAs, and you may regulators 457(b)s.
- This new Internal revenue service represent qualified student loan money (QSLPs) while the money from a worker to help you a being qualified student loan from the personnel, the employee’s mate, or a reliant. The personnel must also be lawfully obligated to create education loan repayments.
- Student loan cosigners aren’t the key individuals. Thus, they are not eligible for a great 401(k) education loan meets.
- All teams just who qualify to receive typical manager-sponsored matches meet the requirements for student loan fits. The regularity off complimentary contributions can vary away from typical boss-meets benefits however, must be one or more times annually.
Suggestions for advancing years bundle providers
- Financing costs created by a worker number towards the fresh annual restrict on elective deferrals.
- Senior years plan providers try not to tend to be specifications you to definitely maximum education loan fits to only certain types of degree funds. All the workers are eligible to receive complimentary contributions on the being qualified pupil financing payments regardless of mortgage types of, attendance at a specific university, or a particular education system. Although not, plans start around has simply appropriate in order to low-collectively bargained teams.