
However, without having a family member to aid and inquire team partners, there is also a share regarding control aspect, therefore be careful off whom you favor.
Here you will find the procedures when planning on taking to see if a beneficial co-candidate plan is very effective to you personally and also the most individual on it:
What makes a man a good Co-applicant?

Whenever choosing an effective co-applicant, you ought to find somebody you faith you to lenders can be, also. It indicates centering on individuals with proper earnings and excellent credit. One says to lenders that individual are capable of their expenses responsibly. High earnings are a beneficial sign that co-candidate gets the money on hands if necessary.
Yet not, on your own peak, loan places Sipsey the new co-applicant have to be people your trust and you will chat openly to help you on your moneymunicate clearly to them to build an effective monetary plan and you can tweak it requisite along the way.
Advantages of That have an excellent Co-applicant
- Greatest Threat of Approval – Applicants with reasonable fico scores (less than 700) provides on a beneficial 32 percent chance of their mortgage app becoming rejected. For those who have another person’s a good credit score in order to right back your right up, you may be expected to listen to that you will be accepted for the individual loans.
- All the way down Interest levels – If the software program is so much more positive, you can aquire better terms.
- Highest Principals – Using this type of, the thing is that extra cash. Two that have a couple of income can afford more substantial household since he’s got a top income to each other. An equivalent idea works for non-married people.
- Possible Credit Benefits – Regardless if their results is reduced, a history of paying off the mortgage promptly can raise their ratings. Make sure you stay on the top of costs, and you may you and others debtor you will see a rise on the credit history. Although not, that it depends on the activities.
- Possible Tax Pros – When itemizing your fees, you could claim taxation write-offs toward mortgage interest money generated through the the season. Definitely consult with a tax top-notch to find out if this is exactly best for you.
What to anticipate While using a great Co-candidate to the a credit card applicatoin
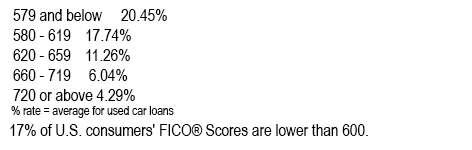
Isn’t it time understand what goes on when you work at co-consumers in application processes? Here’s what understand:
Basic Credit score and you will Credit score Look at
The lender looks at the brand new applicant’s credit score and you will credit history. Ergo, your own previous experiences plays a role in exactly how lenders plan to help. Good credit users that have quick payments mean that you could see more positive financing words.
But not, for those who have a poor credit record, co-borrowing from the bank was greatest. If you find yourself both matched, you have got solid borrowing, plus the financial is far more gonna look positively for you within the software processes.
How the common Providers Works with an effective Co-applicant
Taking out fully that loan is a significant monetary decision, so you should comprehend the measures in techniques. That way, you may have a great deal more belief and will make smarter choices that work for your requirements.
- The lender takes the typical credit rating of your number one applicant and you will co-consumers. Therefore, you don’t need to determine which individual enjoys a far greater reputation becoming indexed since the no. 1 borrower. Each party get equivalent believe.
- Will, the company interacts into the top debtor a great deal more. Ergo, it would be perfect for this option to reside in the newest house, regardless of if its ratings is actually straight down.
- Whenever concentrating on the application form, the firm allows you to include you to definitely the house or property having co-borrowing motives. Like that, he’s liberties toward term, and the shared money of your own top borrower and you can co-applicant is sent on financial group.