
The HELOC application processes is extremely the same as trying to get good mortgage and requirements a comparable documentation and you will fees, also a loan application commission, label lookup, appraisal, attorneys’ fees, and you will items (a share of the count your borrow). Such costs can add on considerably toward price of the loan, specifically if you sooner or later never use far from your own personal line of credit, therefore it is vital that you do the math. Having fun with a HELOC so you can borrow lower amounts may not be well worth they by initial costs and costs.
Within the advice so you can consumers from the domestic collateral fund, new Federal Exchange Fee appetite homeowners to compare loan arrangements out-of certain loan providers, and banking companies, borrowing unions, deals and loans, and financial people. They also encourage borrowers getting transparent about the vetting process. Advising lenders you are looking around allows you to score an effective greatest contract, given that they’ll participate for your needs.
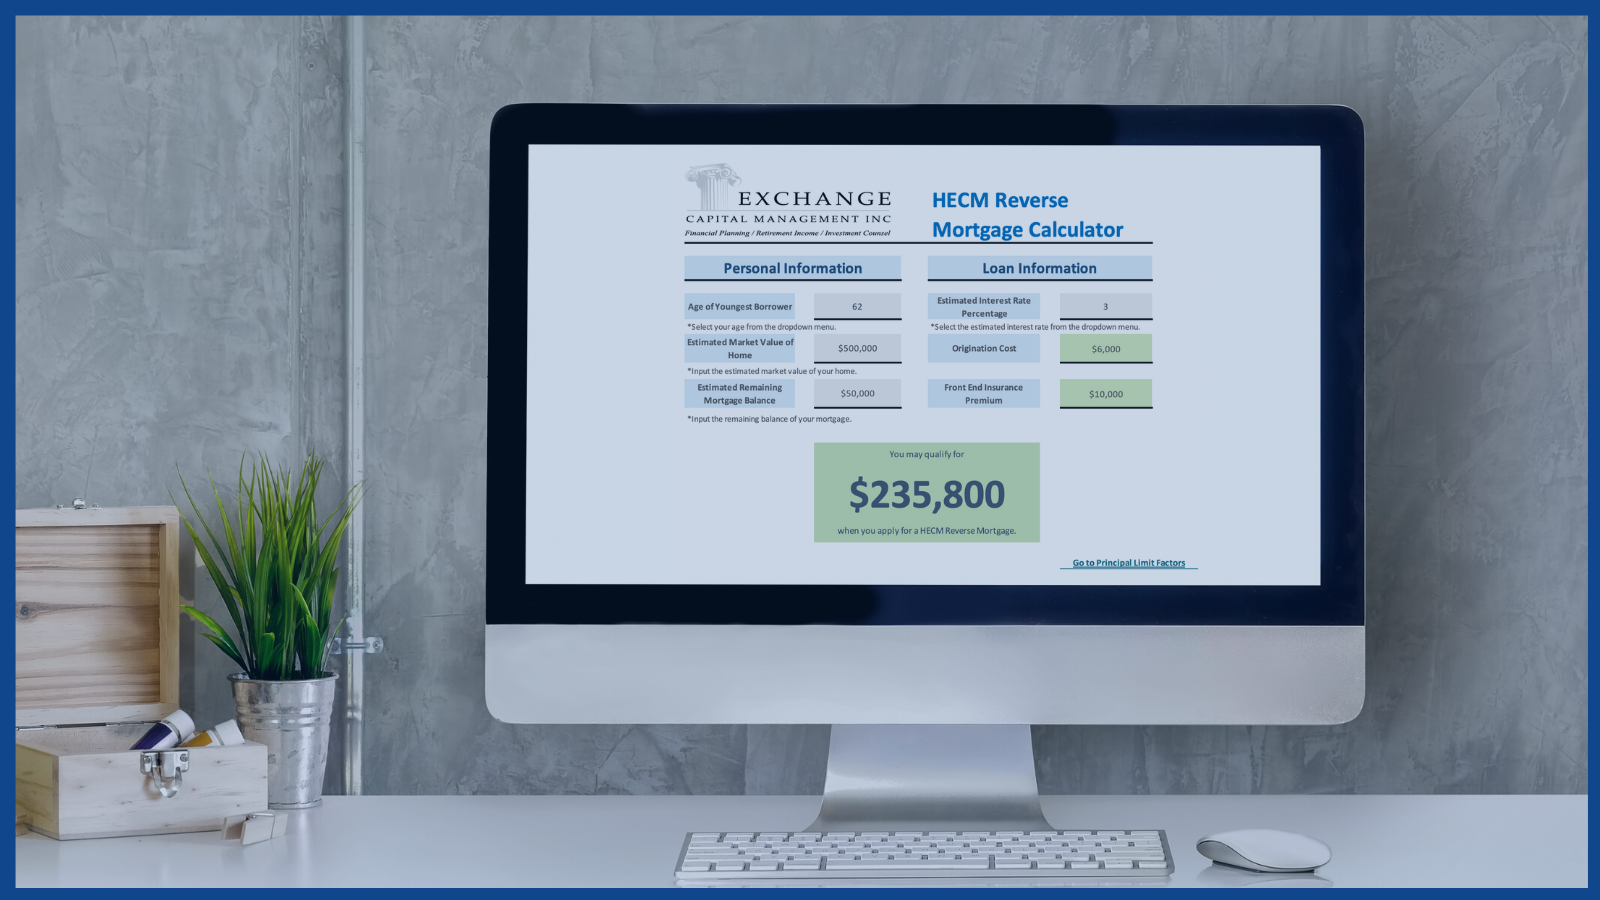
Observe exactly how much you could obtain which have a good HELOC, listed below are some your Realm dash. When you get into your existing mortgage info, you’ll get a precise guess of your own potential HELOC borrowing from the bank electricity, including newest rate rates.
Dive better toward HELOCs
It is not only the cool phrase that is confusing – there are lots of industry slang. But if you’re considering trying to get a good HELOC, it is critical to see these types of conditions and that means you go into talks having loan providers informed and ready to get the very best financing for your position. We have found a quick rundown out-of terms you need to know:
Draw months: An effective HELOC has one or two phase – this new draw period and the repayment period. From inside the draw period, will 10 years, you might use on personal line of credit because of the see, digital finance transfer, or credit cards connected to the membership. Monthly lowest payments are notice-simply when you look at the mark months, you could spend dominant if you want.
Installment several months: During this time, you might not any longer borrow on the financing line. As an alternative, you have to pay right back your loan for the monthly premiums that include dominant and you can attract. By adding dominating, the fresh new monthly premiums normally rise sharply versus mark period. The length of the installment months may vary, whether or not it’s often two decades.
Balloon payment: At the conclusion of the borrowed funds, you could are obligated to pay a large lump sum payment – or balloon percentage – which covers any principal perhaps not paid back when you look at the life of the brand new financing. One which just romantic into good HELOC, consider discussing an expression expansion otherwise refinance option in order that you happen to be secure if you fail to spend the money for lump sum.
Each other occasional and you can lifestyle caps will tell you just how large their money could get and you will if or not you’ll be able to to cover them whether your price rises so you’re able to its limitation.
Contrasting HELOCs, family collateral financing, and money-away refinancing
Good HELOC is not necessarily the only way so you can borrow against the newest guarantee in your home. You may also choose to use the latest also titled (but totally different) family guarantee loan or a cash-aside re-finance. All these alternatives have benefits and drawbacks. Locating the best solution depends on your specific finances and you may means.
To determine what’s best for you, it’s always advisable to keep in touch with an economic elite. Understanding the other financing items will help you most readily useful navigate your own alternatives and you may talks which have economic professionals and you may lenders:
House guarantee financing: A lot of people mistake home security funds having HELOCs. While they’re similar, they might be various other in the extremely important indicates.
- Structure: A personal loan Hamilton TX house equity loan was that loan for a lump sum payment amount, while a HELOC was planned like a great revolving credit line. One another play with house security because the collateral into the loan. With a home security financing, you pay back the mortgage which have equal monthly premiums over a predetermined name, just like your brand-new home loan. In reality, it is an alternate mortgage. Whenever you never pay off the mortgage since arranged, your own lender can also be foreclose on the household.